Self-Employed & Low-Doc Loans in Perth
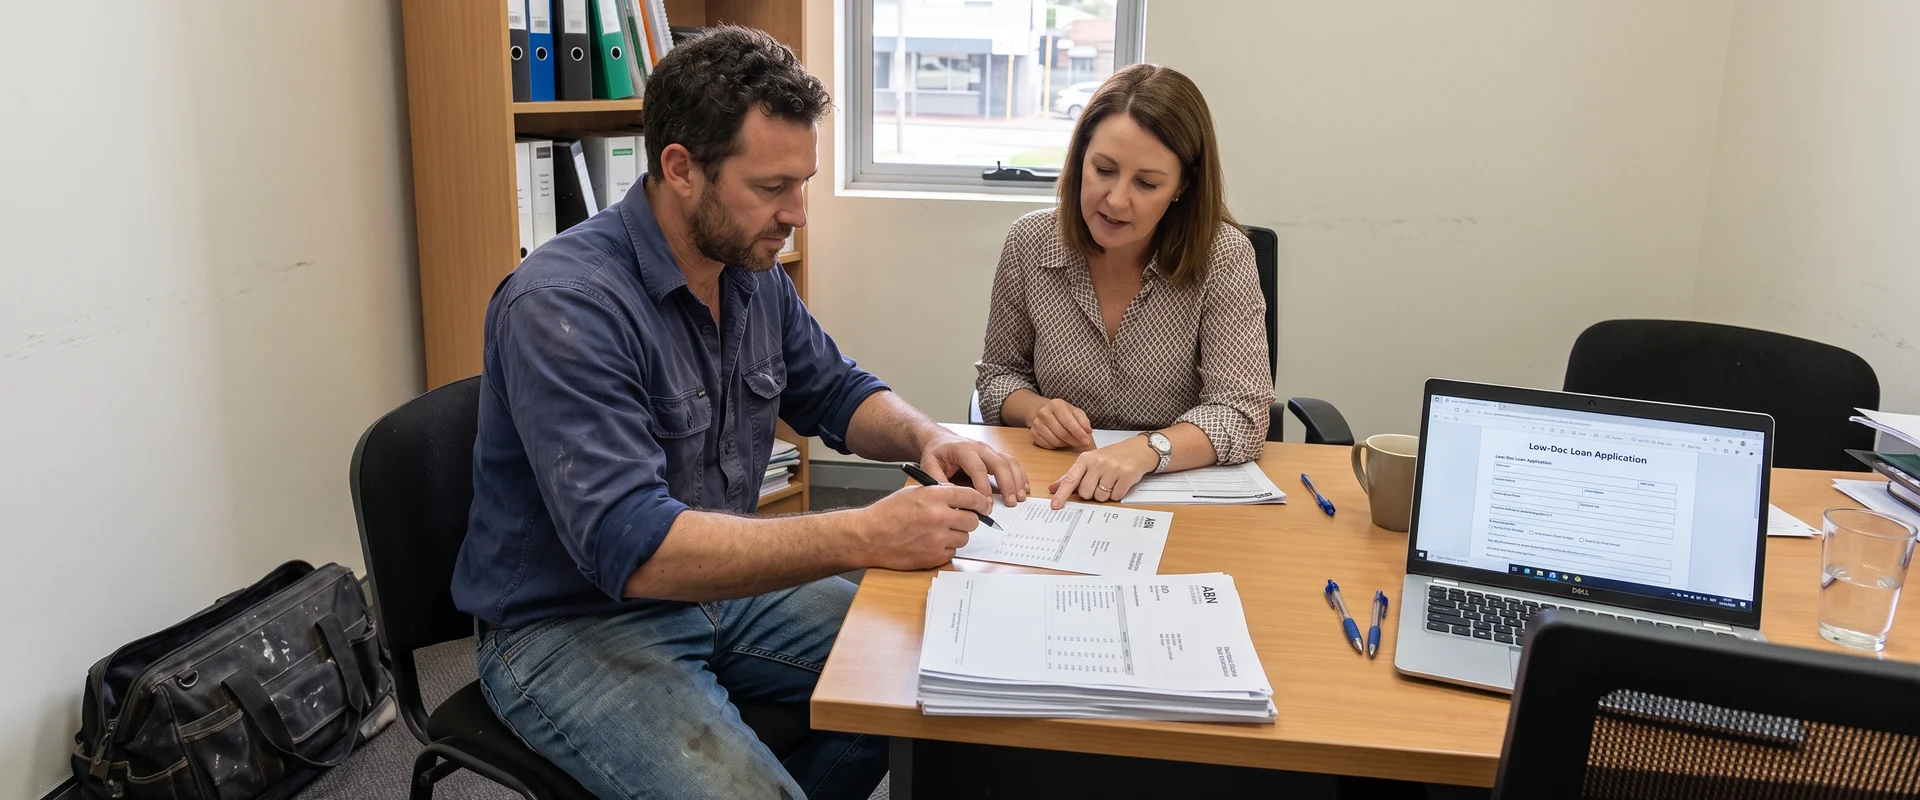
Self-employed and low-doc loans are for Perth buyers who can't show the two recent years of PAYG payslips and tax returns a bank's standard process expects. That covers sole traders, company directors, contractors, and FIFO workers with irregular income. A broker in this category knows which lenders accept alternative evidence, such as BAS statements, an accountant's letter, or business bank statements, and which will only take full tax returns.
What to look for in a broker
- Regular work with self-employed clients, not the occasional one.
- Access to both major banks and non-bank lenders, since low-doc pricing varies a lot.
- A clear explanation of how your income will be assessed before anything is submitted.
- Honest advice on whether you should wait and lodge another tax return to qualify for a cheaper rate.
How our scoring helps
We list 193 businesses in this category. Our scores weigh review evidence, specialisation, and lender access so you can compare brokers on more than a star rating. The approach is set out on our methodology page. To see the top performers across Perth, read the ranked guide to mortgage brokers, then shortlist two or three from this category and ask each how they would structure your application.
Get help choosing self-employed & low-doc loans
Tell us what you need and we'll connect you with local mortgage brokers to discuss your options. No obligation.
All self-employed & low-doc loans, ranked by score and relevance
We found 194 businesses offering self-employed & low-doc loans; 192 met the criteria for the scored directory. The order weighs each business's overall score by how much of its reviewed work is self-employed & low-doc loans, so a lower-scored specialist can rank above a higher-scored generalist. Filter and sort below, or open the full map view.
Quote and contact requests you submit through our forms may be passed to one or more partner providers who can carry out the work, and we may receive a fee for those referrals. Rankings and scores are not influenced by referral fees and remain separate from our independent, published scoring method.
Common questions about self-employed & low-doc loans
- How much does a low-doc loan cost compared with a standard loan?
- Expect a higher interest rate, often around 0.5 to 2 percentage points above standard rates, especially with non-bank lenders. Lower deposits may also mean lenders mortgage insurance or a cap at about 80 percent LVR. Many brokers are paid by the lender, so ask whether you will pay any fee directly.
- Do I need a low-doc loan if I'm self-employed?
- Not always. If you have two years of tax returns and notices of assessment showing steady income, many lenders will treat you as full-doc. Low-doc is mainly for those with a newer business, recent income drops, or heavy tax deductions that lower taxable income.
- What documents will I be asked for?
- Typically an ABN registration date, recent BAS statements, business and personal bank statements, and often an accountant's declaration. Lenders also check your credit history, your deposit and your existing debts.
- How can I tell if a broker is good at self-employed lending?
- Ask which lenders they place self-employed clients with, how they treat add-backs like depreciation, and how long approvals usually take. A good broker will answer specifically and will tell you if waiting would get you a better rate.
Guides to choosing self-employed & low-doc loans
- Self-employed home loan declined? What lenders check and what to do next
Declined for a self-employed home loan? What 6 lenders ask for, your right to a refusal notice and a free credit report, and what to fix before reapplying.